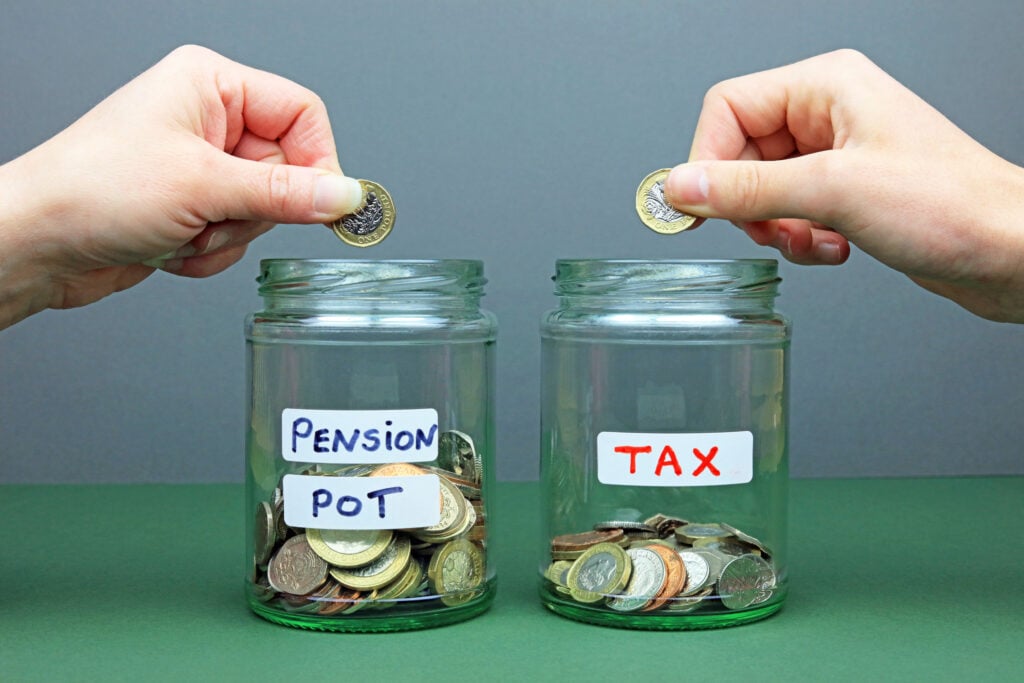
Calls for the government to change Inheritance Tax (IHT) pension legislation to make it “fairer” and give people “greater clarity” have been made by global estate planning body STEP, following the outcome of a recent survey which showed clients are withdrawing pension funds early in response to the reforms.
A pulse survey of 115 people conducted by STEP found that four out of five respondents (all working practitioners) said they have seen clients change their estate or pension planning as a result of government plans to bring unused pension funds and death benefits into the scope for IHT from April 2027.
Clients taking pension money out earlier or sooner than planned was a common change reported by 83% of practitioners, according to the survey, while three in four said to have seen clients increase lifetime gifting.
Further findings from the research included 66% of respondents seeing clients revise their wills or trusts in light of the IHT plans, and 50% noting clients changing who benefits from pensions.
Calls for action have been made by the body in a letter to the Treasury.
Emily Deane, technical counsel and head of government affairs at STEP said: “Currently, the changes contain serious practical flaws that risk creating a catch-22, where families must pay tax before probate is granted, but cannot access funds until probate has been obtained.
“Other practical issues remain unresolved that risk creating difficulties for bereaved families, personal representatives, beneficiaries and pension scheme administrators.”
Back in June, STEP warned IHT plans on pensions, set to come into place in April 2027, will “push people away from pensions” and make family members “increasingly reluctant to take on the executor role”, something the body says is already occurring based on the findings of this survey, with three out of five practitioners reporting seeing clients putting less into their pensions and looking instead for alternatives like ISA accounts to move money into.
Deane highlighted an opportunity for the government to “amend the legislation” so people can “make the most informed and best decisions for themselves, their families and businesses”.
She added: “Without professional advice, the risks of getting it wrong are high and costly. People are potentially jeopardising their later life needs if they withdraw pension funds early, for example, without taking proper advice, or fully understanding the longer-term implications.”
A general consensus from the survey is people are worried by the tax changes that will affect unused pension pots, with 86% of practitioners stating this as the most common concern being raised by clients currently.
Robin Melley, STEP member and managing director of Matrix Capital, revealed there is already evidence of businesses “seeking to exploit the anxiety and fear that the change in IHT rules on pensions has caused”.
“We witnessed this with pension freedoms, in that many people were persuaded to drain their pension pots, which resulted in unexpected income tax charges that were not explained to them, and less income for their retirement,” Melley said. “I have no doubt that the FCA will be busy as the regulator dealing with the fallout to come.”
In a recently released statement by the estate planning body, STEP requested a more detailed roadmap from the government for personal, trust and estate taxation, while appealing for major reforms to be consulted further in advance to ensure “greater stability, predictability and accountability for taxpayers and advisors”.